

Cherry: The Smarter Way to Pay

- 50.00 Reviews
- 4.5
- Downloads
- 100,000+
Our take on Cherry: The Smarter Way to Pay from Appgk
Paying for care, services, or planned purchases can be awkward when the bill arrives before the timing feels comfortable. Cherry: The Smarter Way to Pay is a finance app built around that exact moment: it helps users manage payment plans and pay according to an arranged schedule instead of treating every expense as a single immediate transaction. I found its appeal less in flashy budgeting tools and more in the way it gives a specific payment problem a clearer place on a phone.
That focus matters. Cherry is not trying to be a complete banking replacement, a broad expense tracker, or an investment dashboard. It comes from Cherry Technologies, Inc., and its store category is Finance, but the practical experience is narrower and more purposeful. If you already have a payment plan connected to Cherry, the app is intended to make that plan easier to follow and manage. If you are looking for a general-purpose money manager, the decision is less obvious.
How I Decide Whether Cherry Is Worth Using
My first question with any payment app is simple: does it reduce confusion at the exact point where money needs attention? In Cherry’s case, I would judge it by four things. First, can I quickly understand what plan I am managing? Second, does the scheduled approach fit the way I actually receive and spend money? Third, is the app more convenient than handling the same obligation through a browser, paper statement, or ordinary banking app? Finally, does it stay focused enough that I am not sorting through unrelated financial features?
Those questions are more useful than judging the app by its name or by the promise of paying on a schedule. A plan can look manageable in isolation and still be a poor fit when several other bills land at the same time. I would therefore open Cherry before committing to a payment arrangement only if I already understood the obligation and felt confident that the schedule matched my budget.
Best Parts of Cherry: The Smarter Way to Pay
Things to Keep in Mind About Cherry: The Smarter Way to Pay
The app is free, which removes the most obvious barrier to trying it. It is rated for Everyone, so its presentation is intended for a general audience rather than a specialist financial user. The current release is version 1.3.0, and it requires Android 7.0 or later. Those details make it accessible to many older Android phones, although I would still keep the app updated because payment software is not the place where I want to rely on an outdated installation.
Cherry has an average rating of 4.5 from around one hundred thirty ratings, with about fifty written reviews. More than one hundred thousand people have installed it. I read those figures as encouraging interest rather than proof that it will suit every financial situation. Payment experiences are personal: a person who wants one clear plan may value Cherry highly, while someone who wants full control over every account may reasonably prefer another kind of tool.
News and Features Related to Cherry: The Smarter Way to Pay

News
YouTube Turns a Quick Video Check Into an Hour of Watching

News
BeautyPlus Makes Portrait Retouching Feel Like Your Own

News
TikTok’s Effortless Feed Makes Every Swipe Count—and Every Mistake Harder to Undo
The everyday problem it handles best
Imagine arranging a service when paying the entire amount immediately would make the rest of the month uncomfortable. Instead of leaving the payment details buried in an email or trying to remember a due date from a paper document, you use Cherry as the place to keep track of the plan and make payments on its schedule. That is the kind of ordinary scenario where the app makes sense to me.
The useful habit is to treat the plan as a commitment that needs a place in your monthly routine. I would check it when reviewing upcoming expenses, not only when a payment is already due. That small change can expose a crowded week early enough to adjust other discretionary spending. Cherry does not need to become my entire financial life to be useful; it only needs to make this one recurring responsibility visible and easier to handle.
Don't want to read the full review?
A second practical use is separating planned repayment from everyday spending. A normal bank app may show money leaving an account, but it may not make the reason for that payment especially memorable. Cherry’s plan-centered purpose gives the obligation its own context. For me, that is a meaningful difference when several transactions look similar in a bank statement.
Where the focused design is its strongest advantage
Cherry works best when the payment plan itself is the main thing I need to manage. The narrower purpose can be an advantage because it avoids the clutter found in apps that combine cards, transfers, investments, rewards, spending charts, and account aggregation. When I am dealing with one arranged payment schedule, I would rather see that obligation clearly than hunt for it among unrelated financial data.
Screenshots
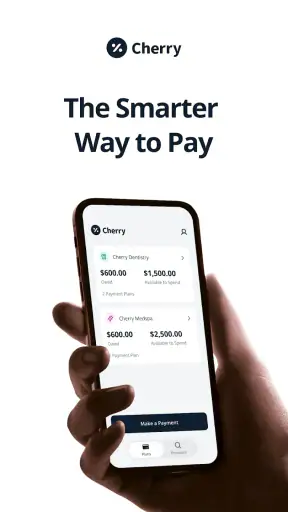
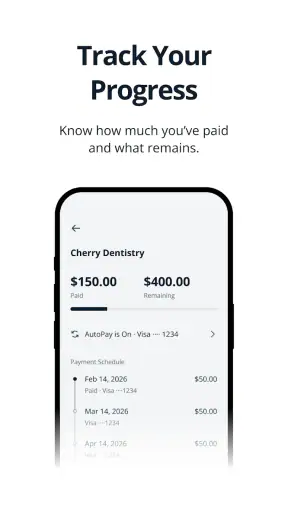
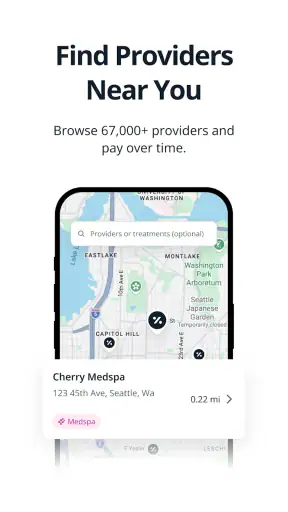
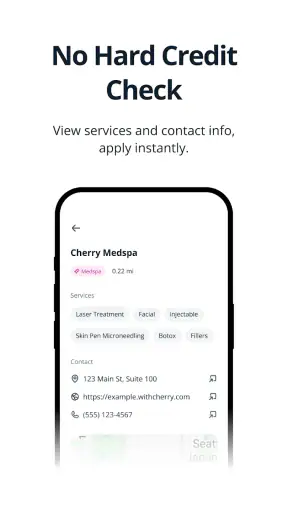
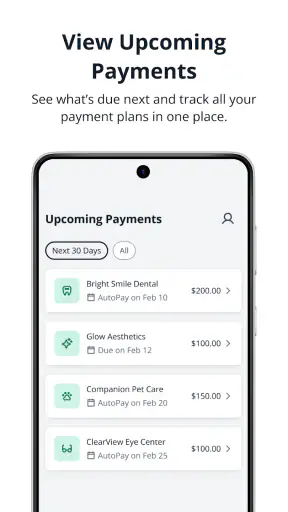
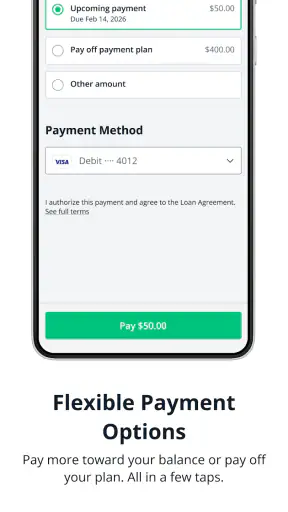
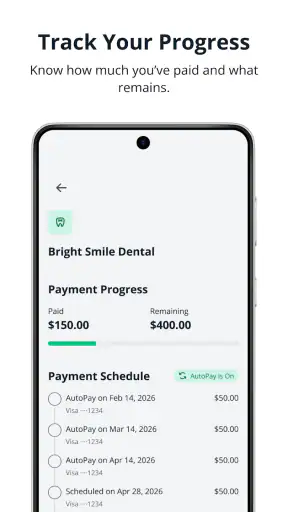
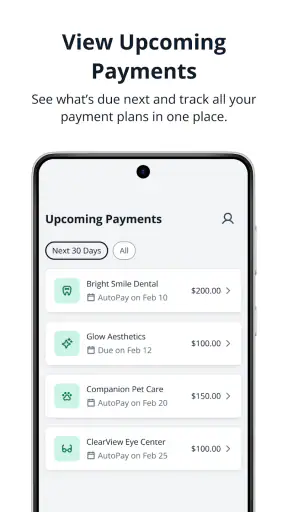
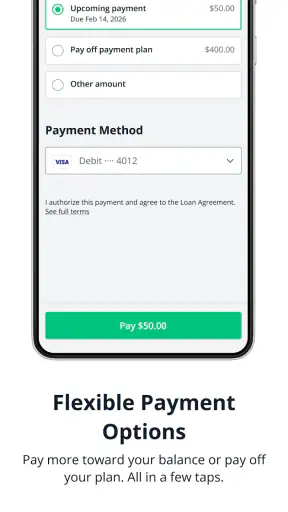
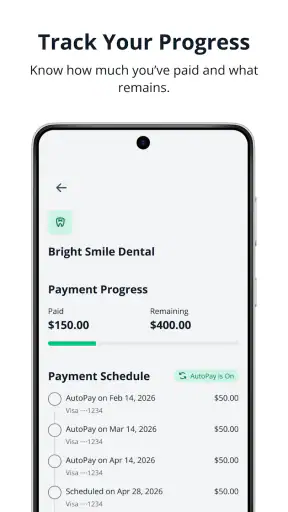
The schedule-based approach also encourages a more realistic view of affordability. A large single bill can feel impossible even when its planned payments are manageable, while a small scheduled amount can seem harmless even when it overlaps with rent, utilities, or other commitments. I would use Cherry as a prompt to look at the whole calendar, not as permission to spend beyond what I can safely repay.
Another strength is that it gives users a dedicated workflow instead of asking them to recreate a plan manually in a notes app or calendar. Those alternatives can remind me that something is due, but they do not provide the same payment-specific context. A spreadsheet offers flexibility, yet it also demands setup and maintenance. Cherry is more appealing when I want less administration and a more direct route to the plan I already have.
I also like the psychological separation. A general banking app is excellent for seeing balances and transactions, but it is designed around accounts. Cherry is designed around a payment arrangement. That difference can help someone who understands their bank balance perfectly well but keeps losing track of why a future payment is scheduled.
Small workflow choices that make the app more useful
My first tip is to review a plan immediately after setting it up, while the original terms are still fresh in my mind. I would confirm the schedule, connect it mentally to the expense it covers, and decide which regular money check-in will include it. The point is not to stare at the app every day; it is to give the plan a reliable place in my routine.
My second tip is to check Cherry before making another large discretionary purchase. A scheduled payment can be easy to ignore when it is spread across time. Looking at the upcoming obligation first creates a useful pause. This is especially valuable for irregular earners, whose income may not arrive in the same pattern as their payment schedule.
My third tip is to use the app alongside, rather than instead of, a broader budget. Cherry can help me manage the Cherry-related plan, but it should not be the only place I assess affordability. I would keep a separate view of rent, utilities, subscriptions, debt, and ordinary spending. The trade-off is clear: the app’s focus makes one plan easier to follow, but that same focus means it is not a complete picture of household finances.
A fourth useful habit is to compare the scheduled payment with the dates when money actually becomes available. Someone paid monthly may think in paydays, while someone with variable income may need a more cautious buffer. I would not assume that a convenient schedule is automatically a comfortable one. The app can organize the commitment, but I still have to decide whether the timing works in real life.
Where the usual alternatives may fit better
The best alternative depends on what I am trying to solve. If I only need a reminder, a calendar or task app may be enough. It is simpler and can cover many kinds of deadlines, but it will not be centered on the payment plan in the same way. If I want to understand every category of spending, a budgeting app is likely a better choice because its purpose is broader than managing one arranged obligation.
A bank app may be preferable when my priority is checking balances, reviewing completed transactions, and moving money between accounts. It is the natural home for general account activity. Cherry becomes more attractive when the question is not merely “how much money left?” but “which payment plan am I following, and what should I expect next?”
A spreadsheet or handwritten budget can be better for people who want complete customization. I can add income cycles, household members, savings targets, and unusual expenses in exactly the format I choose. The cost is effort and the risk of forgetting to update it. Cherry is the more convenient option when I value a dedicated plan workflow over building my own system.
People who dislike scheduled commitments should also think carefully before choosing it. The app can make a payment arrangement easier to monitor, but it does not change the underlying obligation. If I am already struggling with several forms of credit or regularly missing due dates, adding another payment plan may increase pressure even if the interface feels tidy. In that situation, I would first simplify my finances or seek appropriate financial guidance rather than treating a smoother app as the solution.
The cost of switching from another method
Moving from paper, email reminders, or a bank app to Cherry should be fairly easy at the habit level because the main change is where I look for the plan. The real cost is attention. I need to remember that Cherry is now part of my money routine, and I should avoid checking two systems inconsistently. For the first few payment cycles, I would keep my old reminder method active until I was comfortable with the new workflow.
Switching from a detailed spreadsheet is a different decision. I might lose the custom notes and wider financial context that I built myself, even if Cherry makes the payment plan easier to manage. I would preserve those broader records separately and use Cherry for the specific obligation it is designed to organize. That hybrid approach avoids forcing one app to perform two incompatible jobs.
There is also a mental switching cost. A scheduled payment can feel less urgent than a single bill because the amount is distributed over time. I would therefore create a monthly review habit and look at the plan before deciding how much of my remaining income is available. The app can reduce friction, but it should not remove caution.
Because Cherry is free, trying it does not require a purchase decision. Still, free does not mean consequence-free: the payment arrangement remains a real financial commitment. I would read the plan carefully, understand the schedule, and keep enough money available before relying on the app as my main way to manage it.
What I would want a new user to understand first
The first question many people will have is whether Cherry replaces a bank account. I would not treat it that way. Its value is in managing payment plans, while a bank remains the place where broader account activity and balances are handled. Thinking of Cherry as a focused companion prevents unrealistic expectations.
Another likely question is whether it is useful without an active plan. In my view, the strongest reason to install it is having a payment arrangement that belongs in Cherry’s workflow. Without that practical need, a general budget or reminder tool may be more useful for everyday money management.
Users may also wonder whether the app is suitable for a family budget. I would use it for the specific person responsible for the plan, while keeping household income and shared expenses in a separate system. That makes ownership clearer and avoids confusing one payment schedule with the family’s complete financial picture.
For older Android devices, the minimum operating system requirement of Android 7.0 or later is helpful. I would still check that the phone receives security updates and that notifications or account access behave normally after installation. Payment apps deserve more care than casual games because a missed alert or neglected update can affect how confidently I manage an obligation.
Finally, I would not judge the app solely by its rating. The 4.5 average and its growing install base suggest that many users find the concept worthwhile, but the right test is whether the schedule is understandable and manageable for me. A good rating cannot make an unsuitable payment plan affordable.
My recommendation for different kinds of users
I recommend Cherry to someone who already has a relevant payment plan and wants a dedicated, less cluttered way to keep track of it. It is particularly sensible for users who lose payment information among bank transactions, emails, or handwritten notes. The free cost and Everyone age rating make trying it straightforward, provided the underlying commitment is already understood.
I would be more cautious for someone seeking a complete personal finance system. If I need spending categories, investment tracking, shared household planning, or a detailed view across several accounts, I would choose a broader finance tool and possibly keep Cherry as a companion. Its focused design is a benefit only when that focus matches the problem.
I would also skip it if the main issue is unaffordable borrowing rather than disorganized payments. A clearer schedule can help me plan, but it cannot turn an unsafe commitment into a safe one. In that case, the better decision is to review the obligation itself and look for a sustainable solution before adding another app to the routine.
After using it as a decision guide rather than a general wallet, my view is positive but specific. Cherry is most convincing when clarity around one payment plan matters more than having every financial feature in one place. It does not need to replace my bank or budget to earn a place on my phone. For the right user, that narrow purpose is exactly what makes it practical; for everyone else, a broader alternative may be the smarter choice.
Cherry: The Smarter Way to Pay FAQ
What is Cherry: The Smarter Way to Pay?
Cherry is a financing and payment platform that allows customers to split eligible purchases into manageable monthly payments instead of paying the full amount upfront. It is commonly offered by participating businesses, especially in areas such as healthcare, wellness, beauty, and elective services. Availability, payment terms, and approval requirements can vary depending on the merchant, purchase amount, and the customer’s application details.
How does Cherry financing work?
After selecting Cherry at a participating business, you generally complete an application and review the financing options available to you. If approved, you can choose a payment plan, sign the required agreement, and make payments according to the scheduled terms. The exact repayment period, interest rate, fees, and total cost should be checked carefully before accepting, as these details may differ between users and merchants.
Does using Cherry affect my credit score?
Cherry may use credit-related information when evaluating an application, and the effect can depend on the type of credit inquiry and the financing product offered. Some applications may involve a soft check, while accepting a financing agreement or missing payments could have different consequences. Before applying, read Cherry’s current disclosures and the specific terms shown during checkout to understand possible credit reporting impacts.
Are there fees or interest charges when paying with Cherry?
Cherry payment plans are not necessarily free of additional costs. Depending on the offer, you may encounter interest, administrative charges, late-payment fees, or other costs described in the financing agreement. The displayed monthly payment is not the only figure to consider, so review the annual percentage rate, total repayment amount, due dates, and cancellation conditions before confirming the purchase.
What should I do if I cannot make a Cherry payment?
If you expect difficulty making a scheduled payment, contact Cherry as soon as possible through the official app or support channels rather than waiting until the due date has passed. Late or missed payments may result in fees, account restrictions, collection activity, or credit-related consequences, depending on your agreement. Keep your payment method updated and retain copies of all support conversations and confirmations.











